
How Much Life Insurance Do I Need After Buying a Home in Long Beach?
A new home brings new financial responsibilities. Explore what to consider when estimating life insurance needs, including your mortgage, income, existing coverage, and your family’s everyday expenses.
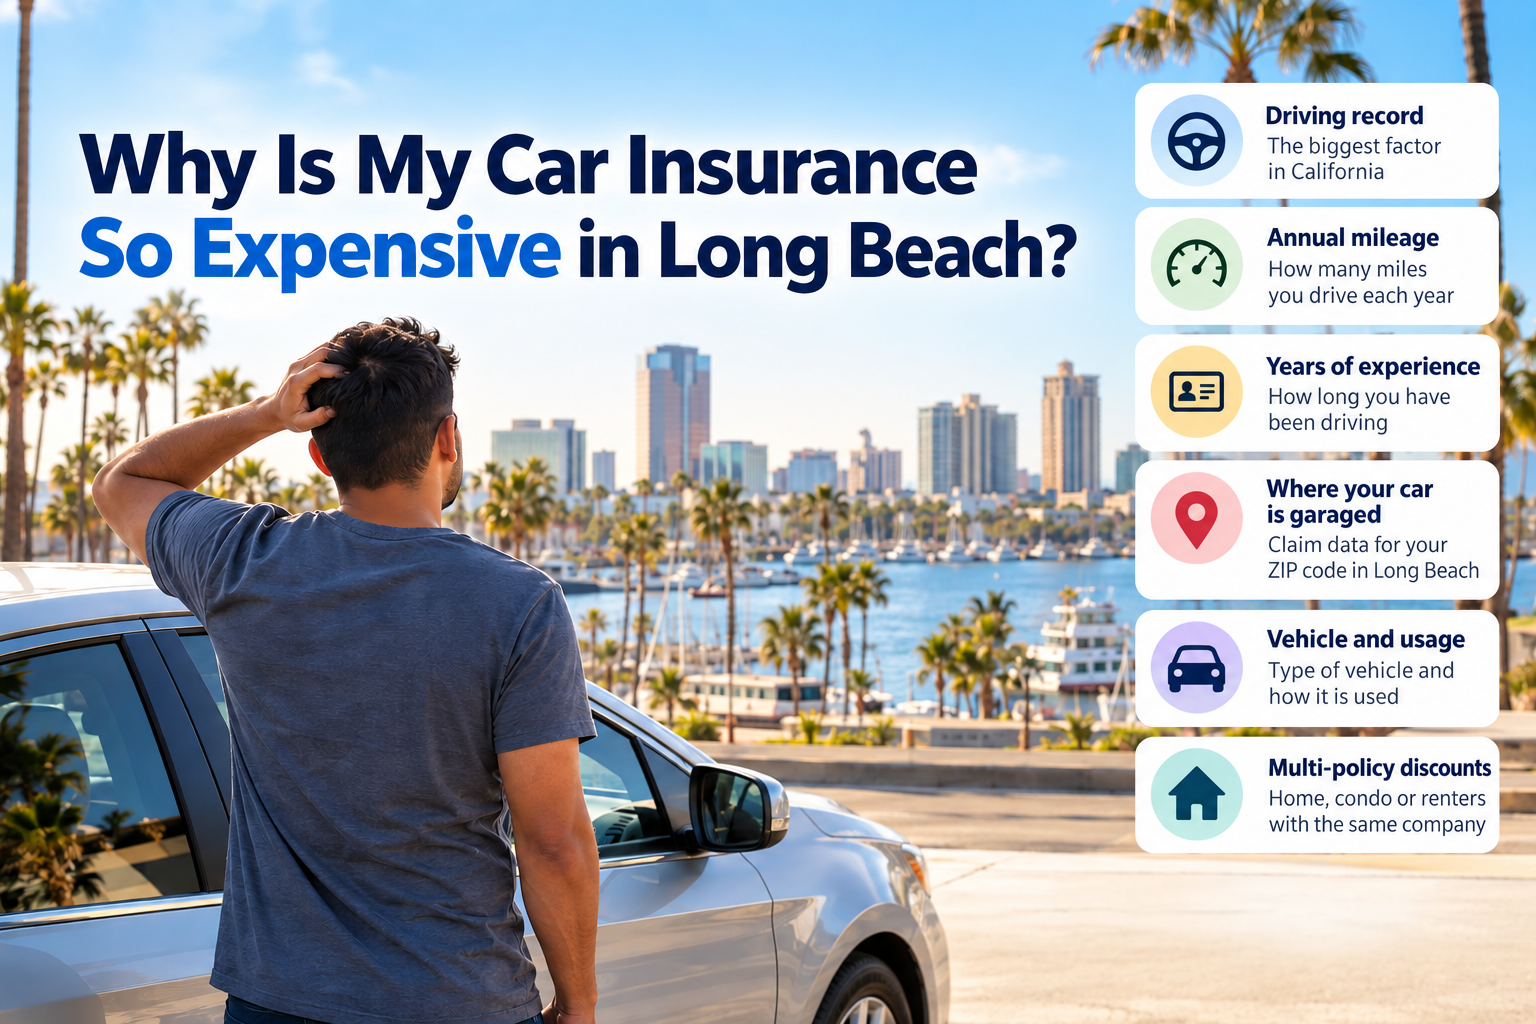
Why Is My Car Insurance So Expensive in Long Beach?
Why is car insurance so expensive in Long Beach? Learn how your driving record, mileage, ZIP code, and coverage choices affect your rate and what you can do to lower your costs.
What Insurance Does a Small Business in California Legally Need?
One coverage is legally mandatory. California Labor Code section 3700 requires every employer with one or more employees to carry workers' compensation insurance. General liability, commercial property, and commercial auto are not state-mandated for most businesses, but leases, clients, and lenders require them routinely.
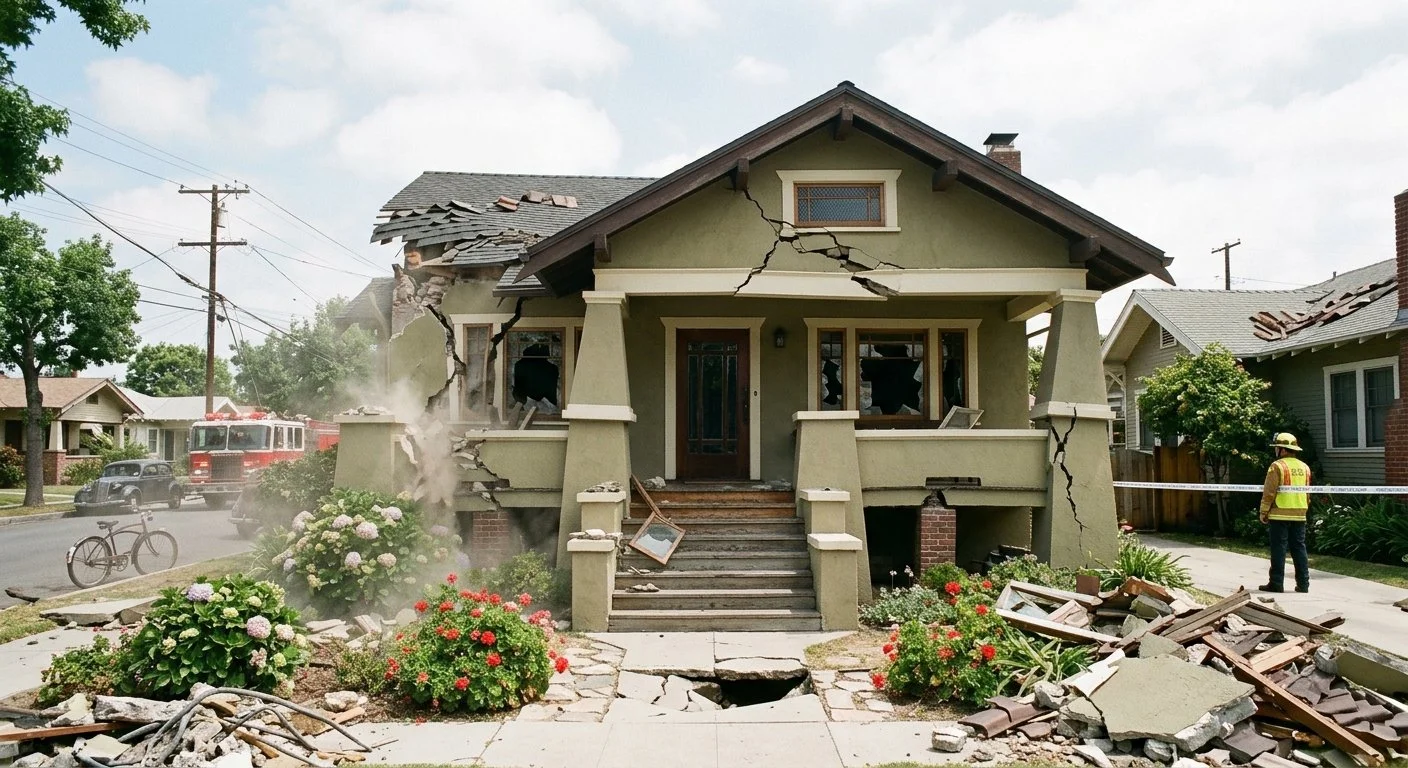
Does Homeowners Insurance Cover Earthquake Damage in California?
No. A standard California homeowners policy excludes earthquake damage, and so do standard condo and renters policies. Earthquake coverage must be purchased separately. Most California policies are written through the California Earthquake Authority, which sells homeowners, condo unit owner, and renters coverage through participating insurers.
Does My Landlord's Insurance Cover My Belongings?
No. Your landlord's policy covers the building, not what is inside your unit. If a fire, a burst pipe, or a burglary damages your furniture, electronics, or clothing, that policy pays nothing toward replacing them. A renters policy is what covers your property, and it covers your liability as a tenant.
How Much Car Insurance Does California Actually Require?
California's minimum car insurance limits rose to 30/60/15 in 2025. See what the numbers mean and why many Long Beach drivers carry more than the minimum.