Commercial Auto Insurance in Long Beach
Who needs commercial auto insurance
A vehicle registered to your business needs coverage that meets California's financial responsibility minimums, which since January 1, 2025 are $30,000 for injury to one person, $60,000 per accident and $15,000 for property damage. Beyond registration, use is what decides it. A truck titled to you personally but driven to job sites often falls outside a personal auto policy, because personal policies commonly exclude or limit business use.
Businesses that operate as motor carriers of property face higher requirements, including a $750,000 combined single limit for most carriers under California Vehicle Code section 34631.5. Contracts and leases can set limits too, and a client's vendor requirements may ask for a certificate of insurance.
What commercial auto insurance covers
A commercial auto policy generally includes liability for injury and damage you cause with a covered vehicle, physical damage to the vehicle itself through collision and comprehensive coverage, uninsured and underinsured motorist coverage for the people in your vehicles, and medical payments. Limits and options vary by policy and carrier, and we walk through them in plain terms before you decide.
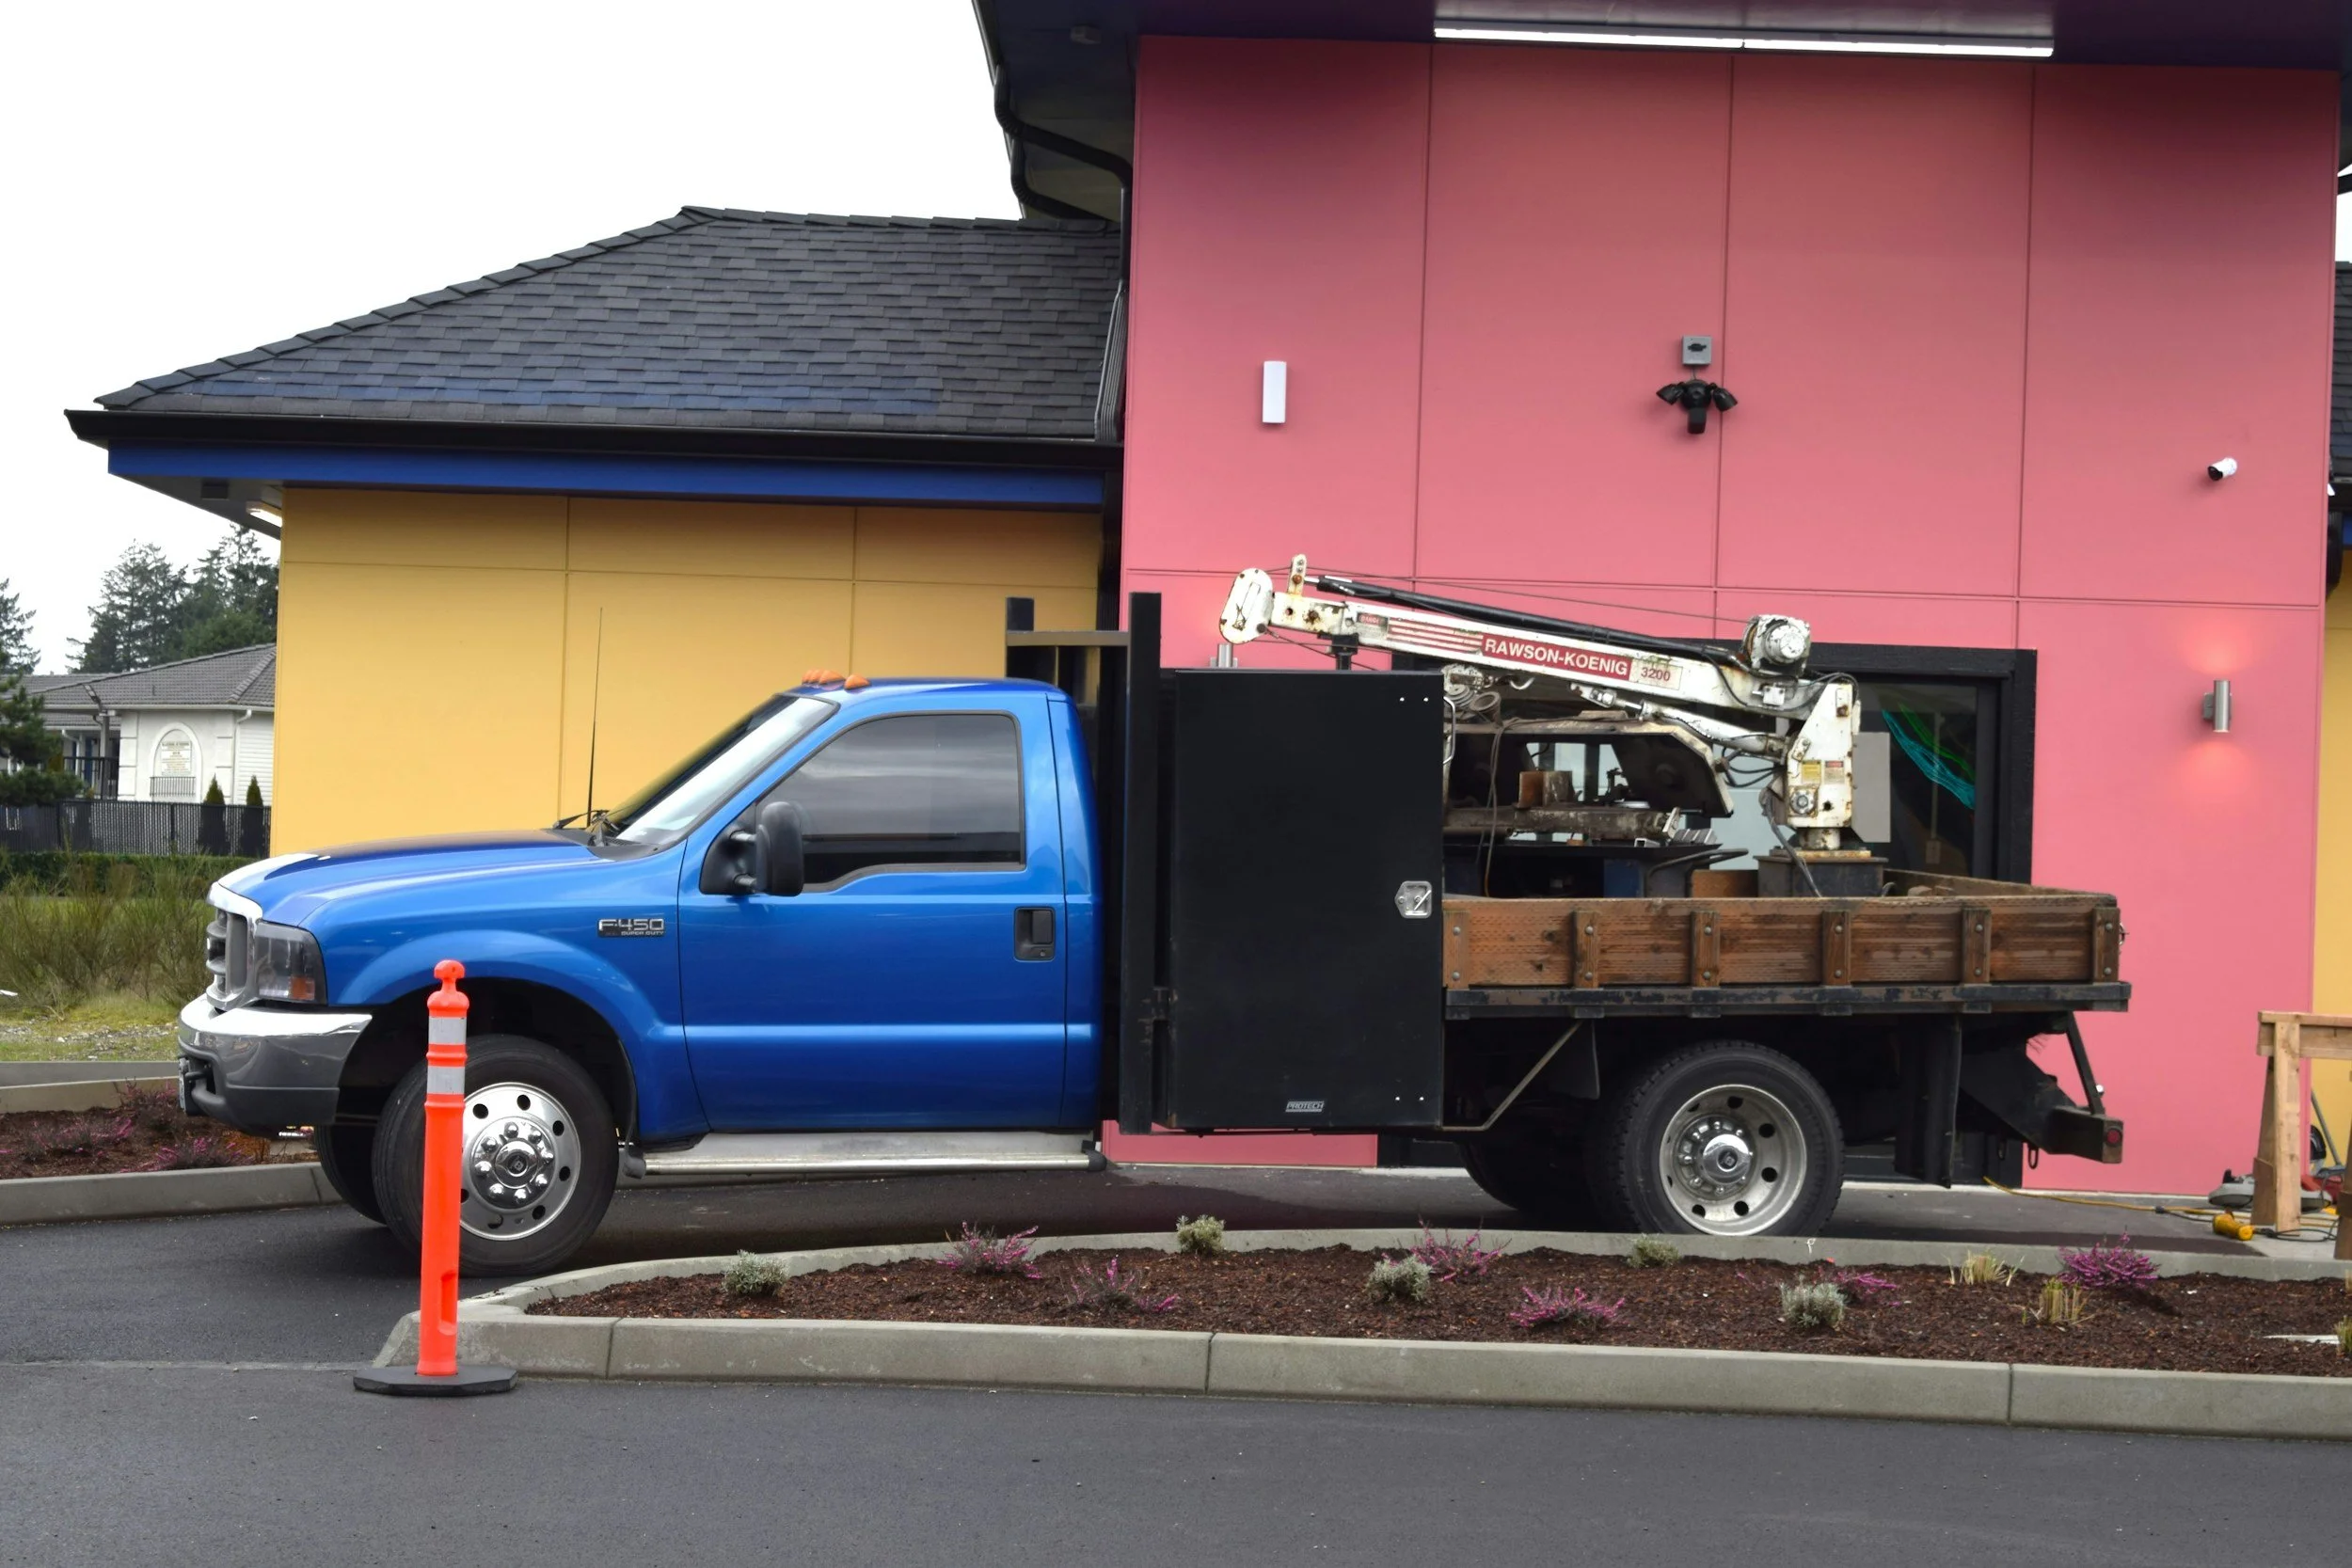
The truck's policy generally pays for the truck, not the tools, equipment or cargo inside it. That contents coverage is a separate line, often called tools and equipment or inland marine coverage, and cargo in transit needs its own place on the policy.
Vehicles your business does not own are a different question. An employee's car on a work errand, or a rental for a trade show, calls for hired and non-owned auto liability, because a general liability policy is written to exclude autos.
What it does not cover on its own