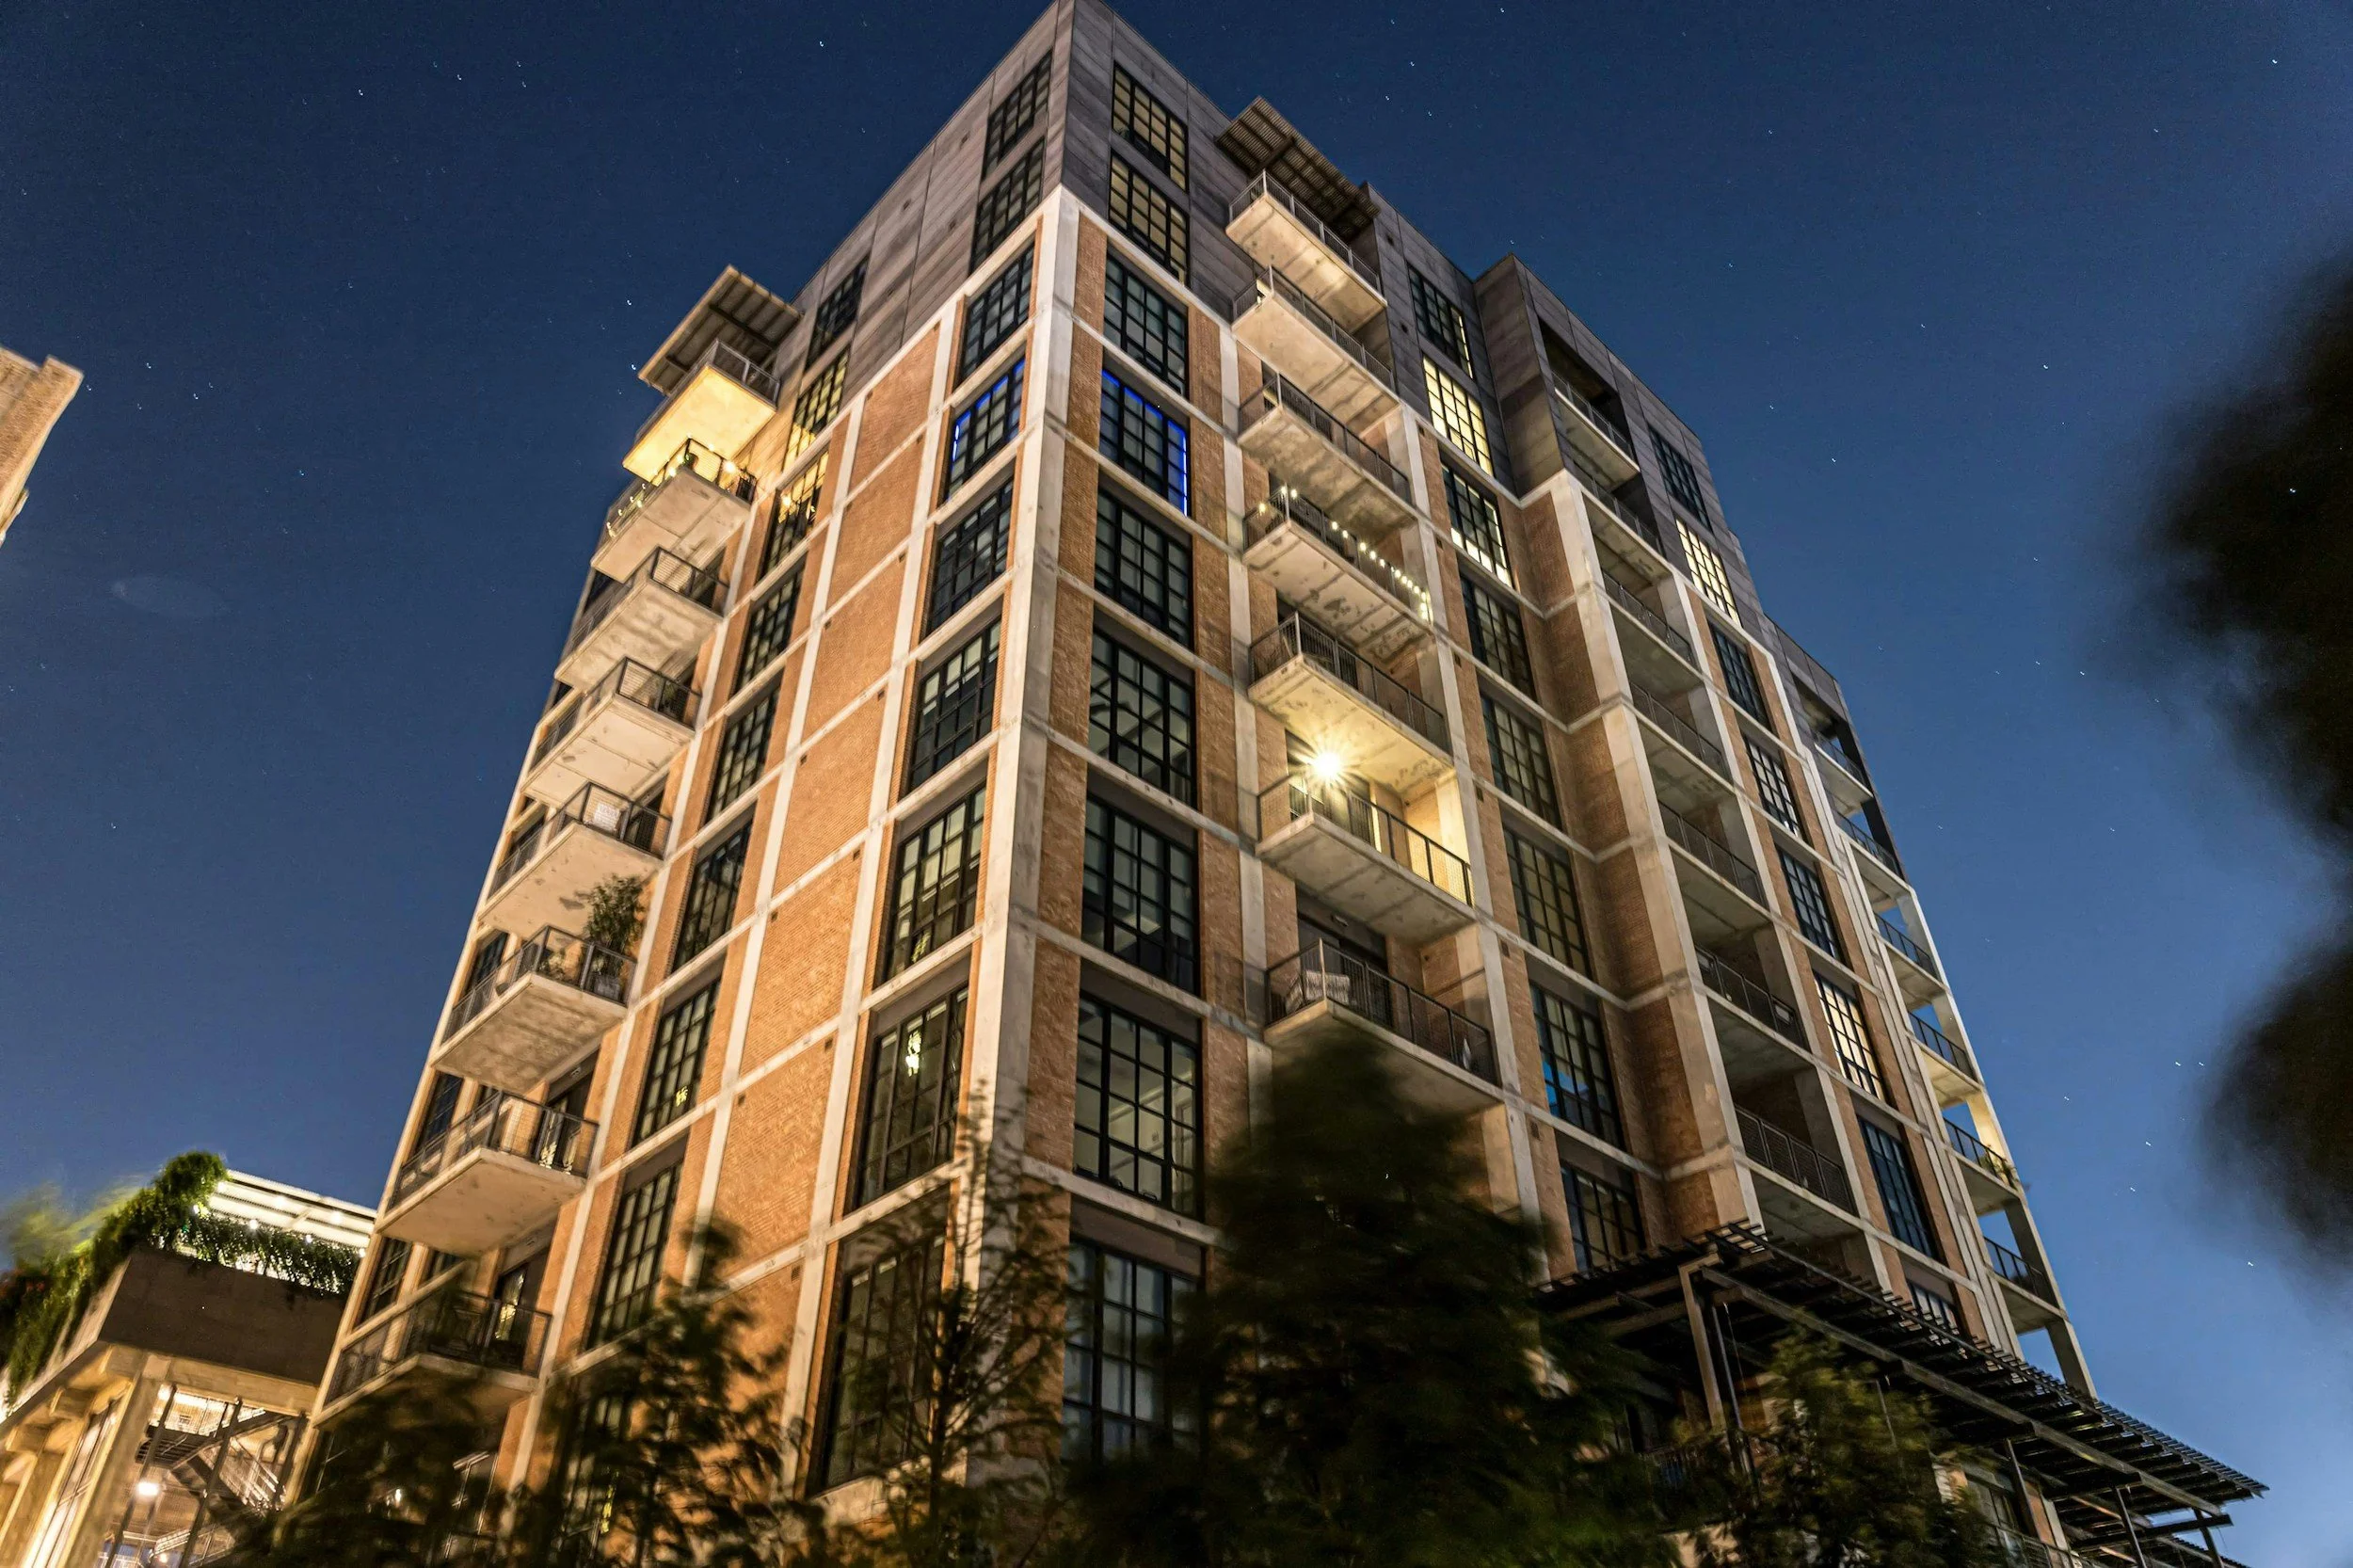
Condo Insurance in Long Beach
Coverage includes your unit’s interior, such as flooring, cabinets, fixtures, appliances, and improvements you’ve made. It also includes your personal belongings, personal liability if someone is hurt inside your unit, and loss of use while your unit is being repaired.
And one coverage most owners have never heard of: loss assessment. If the building has a large claim, the HOA can charge each owner a share of the cost, and this coverage helps pay that bill. It is usually inexpensive and usually the reason someone is glad they called us.
What it covers
The building structure, common areas, and anything the master policy already handles. Earthquake and flood are separate.
The trap is the middle ground. Master policies come in different forms. A “bare walls” policy stops at the studs and leaves you responsible for everything from the drywall inward. An “all-in” policy covers the original fixtures but not your upgrades. Two owners in the same building with identical units can need very different policies depending on what each one has renovated.
What it doesn’t cover
A lot of local condo stock is in older buildings and in the downtown and Ocean Boulevard towers, and HOA master policy deductibles have been climbing. That matters more than it sounds: when the master deductible is large and the building has a claim, the HOA often passes the cost to owners by assessment. Loss assessment coverage is what stands between you and a five-figure bill you had no say in.
Send us your HOA’s master policy declarations page along with your quote request. We’ll tell you exactly where it stops.
How much condo insurance do I need?
The right amount comes from four separate numbers, and only one of them is about your belongings. Use them as a checklist, then compare each one with your HOA's master policy declarations page so that nothing is insured twice and nothing falls between the two policies.
The first is coverage for the inside of your unit. Your HOA's master policy insures the building to a level set by your CC&Rs, either to the bare walls or including fixtures and finishes. Whatever the master policy does not insure, such as flooring, cabinets, countertops and upgrades you made, is yours to cover. Read the insurance section of your CC&Rs before you pick a limit.
The second is personal property. Walk through the unit room by room and add up what it would cost to replace everything you own, not what you paid. Ask whether the policy pays replacement cost or depreciated value.
The third is liability. If a guest is hurt in your unit, or water from your unit damages the one below, this is the coverage that responds. It protects your savings and future income, so the number should reflect what you have to protect.
The fourth is loss assessment. When a large claim exceeds the master policy or its deductible, the association can bill owners for a share, and this coverage can help pay that bill. The limit on many policies is modest unless it is raised.
Standard condo policies exclude earthquake damage, which is sold separately, so it is worth asking about even though it is not part of the basic policy. Owners in Naples, downtown and along the shoreline often start with two documents: the HOA's master policy declarations page and its annual insurance summary. Bring both and we will read them with you.
Call (310) 734-6151 or stop by 4510 E Pacific Coast Hwy Ste 450, Long Beach, CA 90804.
Additional facts